Advertisement

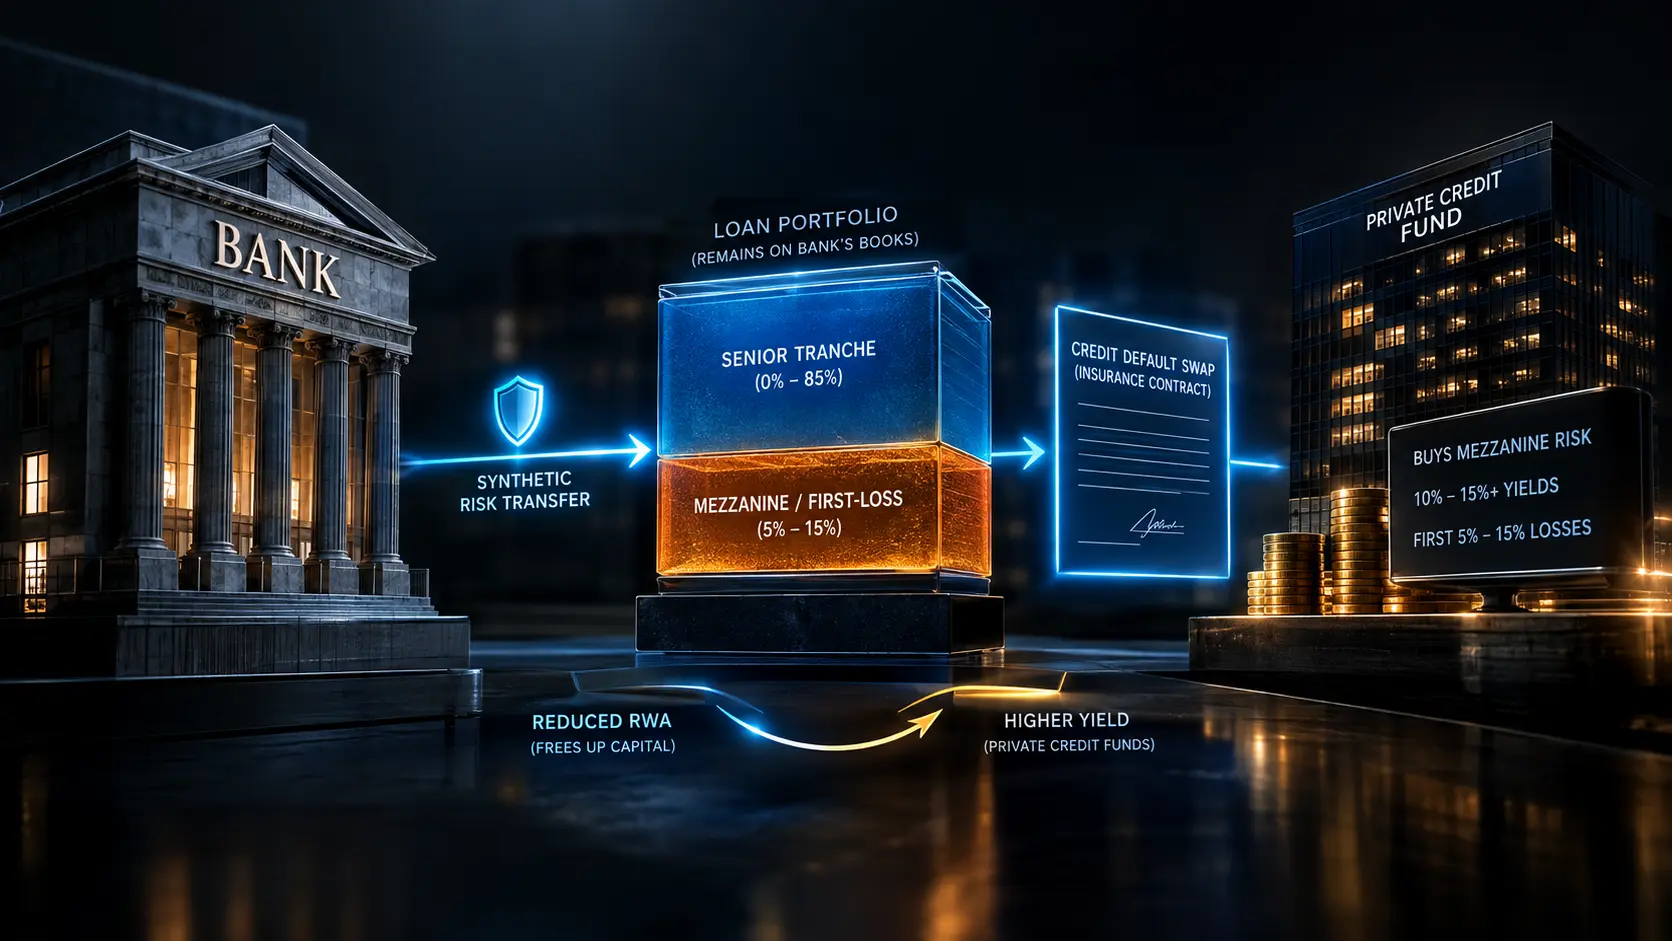

Global banking regulators are squeezing the lifeblood out of Wall Street lending. In the wake of regional banking collapses and the implementation of the Basel III “Endgame” frameworks, the Federal Reserve and the European Central Bank have issued a brutal mandate: banks must drastically increase the cash they hold in reserve against every loan they write. When capital sits in a vault acting as a regulatory buffer, it earns zero yield. For a Tier-1 bank with a trillion-dollar corporate loan book, this regulatory capital drag destroys return on equity (ROE) and paralyzes new lending. Banks needed a loophole to make the risk disappear without losing their clients.
Why should you care right now? Because Wall Street found the loophole, and it is reshaping the global credit markets. It is called a Capital Relief Trade (CRT). Instead of selling the actual loans, banks are quietly purchasing exotic insurance policies from massive private credit funds to cover the default risk. By synthetically transferring the risk of the loan to a shadow lender, the bank satisfies the regulator, instantly freeing up billions of dollars in trapped capital. For private credit funds, buying this risk unlocks double-digit yields on prime corporate debt they could otherwise never access. CRTs are the invisible structural pipes currently keeping the global financial system highly leveraged and heavily intertwined.
What are Capital Relief Trades (CRTs)?
Capital Relief Trades (CRTs), or Synthetic Risk Transfers (SRTs), are financial transactions where a bank pays a private investor to assume the default risk of a specific loan portfolio. The bank retains ownership of the loans, but synthetically transferring the risk allows the bank to drastically reduce its regulatory capital requirements under Basel III.
At a Glance
- Concept: Buying an insurance policy on a pool of loans so regulators let you hold less cash in reserve.
- Why it matters: Banks are legally required to hoard capital. CRTs allow them to free up billions of dollars overnight to issue new loans or buy back stock.
- Who uses it: Mega-banks (JPMorgan, Santander, Barclays) selling risk, and private credit giants (Ares, Blackstone, PGGM) buying the risk.
- Biggest takeaway: The loans are never actually sold. The transaction is entirely synthetic, meaning the corporate borrower has no idea that a hedge fund is secretly on the hook if they go bankrupt.
In Simple Words
Imagine you are a bank that just lent $\$100$ million to 100 different businesses. The government regulator steps in and says, “Lending is risky. You must lock $\$10$ million of your own cash in a vault just in case those businesses go bankrupt and you lose money.”
That $\$10$ million is now dead money. You can’t use it to make new loans or pay dividends.
To solve this, you call a hedge fund. You say, “I will pay you a massive 12% interest rate every year. In exchange, if any of these 100 businesses go bankrupt, you cover the losses, not me.”
You show this contract to the government regulator. The regulator says, “Since the hedge fund is taking the risk now, you don’t need to hold the $\$10$ million in the vault anymore.” You unlock your cash, the hedge fund gets a massive yield, and the businesses never even knew the deal happened. This is a Capital Relief Trade (CRT).
Why This Matters
For Institutional LPs, Corporate Treasurers, and Credit Analysts, CRTs solve the Risk-Weighted Asset (RWA) Trap.
Every loan on a bank’s balance sheet is assigned a Risk Weight. A prime corporate loan might have a 50% risk weight, while a sketchy commercial real estate loan might have a 150% risk weight. Under Basel III, the higher a bank’s total Risk-Weighted Assets (RWA), the more hard capital it must hold.
For the last decade, if a bank wanted to lower its RWA, it had to perform a “True Sale”—physically selling the loans to another institution. But selling a loan ruins the client relationship. If JPMorgan sells a corporate revolver to a hedge fund, the corporate client gets angry and takes their investment banking and treasury business elsewhere.
CRTs separate the risk from the relationship. By executing a synthetic transfer via a credit default swap or financial guarantee, the bank reduces its RWA calculation without ever alerting the client.
Micro-Insight: In capital markets, whoever owns the client relationship controls the pricing power. CRTs allow banks to outsource the raw capital risk while maintaining absolute control over the highly profitable client relationship.
The Convergence of Banks and Private Credit
We are witnessing the final Convergence of Traditional Banking and Shadow Banking.
For decades, regulators treated banks and private asset managers as separate ecosystems. CRTs formally link them. Banks have the massive distribution networks required to originate loans, but they lack the regulatory capital to hold them. Private credit funds have billions in un-deployed capital, but they lack the infrastructure to originate prime corporate loans at scale. CRTs are the symbiotic bridge—banks become origination engines, and private credit becomes the ultimate balance sheet.
How Capital Relief Trades (CRTs) Work
Moving billions of dollars of risk off a balance sheet without moving the underlying assets requires precise financial engineering. Here is the first-principles breakdown of the architecture.
1. The Fundamental Problem: Capital Drag
A bank holds a $\$2$ billion portfolio of performing corporate loans. Under Basel III, the regulator requires the bank to hold 8% to 10% of that portfolio’s risk-weighted value as Tier-1 capital. This translates to roughly $\$150$ million in cash locked in a vault earning nothing, severely depressing the bank’s Return on Equity (ROE).
2. The Core Mechanism: Synthetic Transfer
To release the capital, the bank groups these loans into a “reference portfolio.” The bank does not sell the portfolio. Instead, it enters into a synthetic securitization contract (often structured as a Credit Default Swap or a Credit Linked Note) with a private credit fund.
3. Technical Depth: Mezzanine Tranching
The bank does not transfer all the risk. It slices the risk into tranches. The bank retains the “Senior” tranche (e.g., 0% to 85% of the portfolio), which almost never defaults. The bank then sells the “Mezzanine” or “First-Loss” tranche (the riskiest 5% to 15%) to the private credit fund.
Because the private credit fund is now absorbing the first $\$100$ to $\$300$ million of absolute losses if businesses in the portfolio start going bankrupt, the regulator views the entire $\$2$ billion portfolio as fundamentally “de-risked.”
Plain-English Takeaway: The bank buys insurance that specifically covers the first 10% of losses. Because it is statistically nearly impossible for a prime loan portfolio to suffer more than a 10% loss rate, the regulator treats the portfolio as essentially risk-free.
4. Technical Depth: Blind Pools and Replenishment
To prevent insider trading, the private credit fund is rarely allowed to see the exact names of the 500 corporations in the portfolio—this is known as a “blind pool.” They only see anonymized credit metrics (e.g., “Software Company, BBB rating, $10M revenue”). Furthermore, as old loans are paid off, the bank is allowed to “replenish” the pool with new loans that fit the same risk parameters, keeping the CRT active for 5 to 7 years.
5. Real-World Consequences: RWA Optimization
The moment the contract is signed, the regulator permits the bank to drop the RWA of the portfolio drastically. The $\$150$ million in trapped capital is instantly released back to the bank. The bank uses this unlocked cash to issue a brand new $\$2$ billion loan portfolio, effectively doubling their lending capacity using the exact same amount of underlying capital.
Capital Relief Trade (CRT) Simulator
Synthetic Securitization, RWA Optimization & Systemic Shadow Banking Risks
Mezzanine Risk Transfer
0%
Underlying Asset Type
Prime Corporate
Subprime Auto
Trapped Regulatory Capital
$160M
Bank Return on Equity (ROE)
12.5%
Private Credit Yield
0.0%
Synthetic Risk Flow & Balance Sheet Mechanics
UNHEDGED: CAPITAL TRAPPED
Capital Efficiency & Yield Generation Over Time
Real-World Applications
Capital Relief Trades have exploded from a niche European regulatory workaround into a global, multi-asset-class standard.
European Corporate SME Portfolios: European banks (like Santander and Barclays) have historically relied far more heavily on keeping corporate loans on their balance sheets compared to US banks (which typically securitize and sell them immediately). Because European banks are fundamentally balance-sheet constrained, they execute massive CRTs on their Small and Medium Enterprise (SME) lending books. By transferring the mezzanine risk of thousands of small businesses to pension funds like PGGM, European banks maintain domestic lending capacity without breaching ECB capital limits.
Auto Loans and Consumer Credit: In the US, banks like Ally Financial and US Bank are applying CRT mechanics to auto loans. Instead of physically packaging car loans into Asset-Backed Securities (ABS) and selling them to the public market—which incurs heavy legal and underwriting fees—the bank keeps the auto loans on its books and executes a bilateral synthetic CRT with a single private credit mega-fund (like Ares or Blackstone). This reduces transaction friction and executes in weeks rather than months.
Subscription Lines for Private Equity: Banks provide massive “capital call” or subscription lines of credit to private equity funds. These are incredibly safe loans, but under Basel III, they still consume heavy RWA. Banks are now structuring CRTs specifically around these pristine private equity credit lines, paying specialized hedge funds a premium to absorb the mathematically near-zero risk of default, strictly to optimize their regulatory ratios.
Economic & Strategic Impact
The core strategic consequence of the CRT boom is the Obfuscation of Systemic Risk.
In a traditional market, if you want to know who holds the risk of corporate bankruptcies, you look at the balance sheets of the major banks. CRTs render bank balance sheets fundamentally opaque. The bank holds the loan, but the risk of default has been silently exported to unregulated shadow entities—private credit funds, family offices, and sovereign wealth funds located in offshore jurisdictions.
While regulators praise CRTs for making the core banking system safer (by dispersing risk), systemic credit analysts warn of the “Blind Spot” effect. During a synchronized macroeconomic recession, if corporate defaults spike above the 10% mezzanine threshold, the private credit funds absorbing these losses could face severe liquidity crises. Because these funds are largely unregulated and operate outside the purview of the Federal Reserve, a cascading failure in the shadow banking sector would occur entirely in the dark.
Advantages of Synthetic Risk Transfers
- RWA Optimization: Instantly frees up trapped regulatory capital, allowing banks to increase Return on Equity (ROE) and issue new loans.
- Relationship Preservation: Unlike a true sale, the bank keeps the loan on its balance sheet. The corporate borrower never knows their risk was transferred, preserving the client relationship.
- Speed and Privacy: Bilateral synthetic transfers with a single hedge fund avoid the massive legal fees, public disclosures, and SEC filings required for traditional public securitization.
- Yield Generation for LPs: Provides institutional investors access to diversified, prime bank loan portfolios that they physically cannot originate themselves, yielding 10% to 15%+.
Risks and Limitations of CRTs
- The Cost of Protection: The bank must pay a hefty premium to the private credit fund (often SOFR + 8% to 12%). This severely eats into the net interest margin of the underlying loan portfolio.
- Blind Pool Friction: Because investors cannot see the exact names of the borrowers in the portfolio, they must price in a “blindness premium,” assuming the bank is packing the pool with slightly riskier assets (adverse selection).
- Counterparty Risk: If the private credit fund goes bankrupt during a severe recession, the synthetic insurance policy becomes worthless. The risk instantly boomerangs back onto the bank’s balance sheet exactly when the bank can least afford it.
Takeaway: A CRT is an expensive accounting hack. The bank willingly gives up a significant portion of its profit margin on the loan in exchange for the regulator allowing them to free up the capital to do the trade again.
Common Misconceptions
Misconception: CRTs are exactly the same as the Collateralized Debt Obligations (CDOs) that caused the 2008 crash.
Reality: 2008 CDOs were structurally flawed because banks sold the entire risk, incentivizing them to originate garbage loans (subprime mortgages) because they held zero liability. In modern CRTs, the bank must retain a massive “skin in the game” tranche (both the senior piece and a vertical slice of the risk) specifically to ensure their underwriting standards remain pristine.
Misconception: The bank is actively trying to get rid of bad loans.
Reality: Private credit funds are highly sophisticated. They will not buy a CRT if they suspect the bank is dumping toxic waste. Banks typically put their highest-quality, most boring corporate loans into CRT pools to ensure the pricing of the insurance remains cheap.
Misconception: CRTs are illegal regulatory arbitrage.
Reality: CRTs are explicitly codified and encouraged by both the Federal Reserve and the European Banking Authority. Regulators want banks to disperse risk into the private markets to prevent the banking sector from taking down the economy during a crash.
What Most People Miss
The disruptive capability of The Replenishment Squeeze.
A standard CRT lasts for roughly 5 to 7 years. Because corporate loans (especially revolvers) are often paid off in 2 to 3 years, the bank negotiates a “replenishment period.” As old loans pay out, the bank can slot new loans into the CRT structure to keep the insurance active.
However, the private credit fund sets strict mathematical parameters on what can be added (e.g., “No more than 5% exposure to the tech sector, no rating below BB”). During a rapidly shifting economic environment, the bank may struggle to find new loans that fit these exact, pre-negotiated parameters. If the bank cannot replenish the pool, the size of the CRT shrinks, the capital relief vanishes, and the bank is suddenly forced to hoard cash again at the worst possible time.
Comparison Table
| Metric | Unhedged Bank Loan | True Sale Securitization (ABS) | Synthetic Capital Relief Trade (CRT) |
| Asset Ownership | Bank | Sold to SPV / Investors | Bank (Retains on balance sheet) |
| Client Relationship | Intact | Severed or disrupted | Intact (Invisible to client) |
| Regulatory Capital | Extremely High (Capital Trapped) | Zero (Off balance sheet) | Low (Risk transferred synthetically) |
| Execution Speed | Instant | Slow (Months of SEC filings) | Fast (Bilateral private contract) |
| Risk of Boomerang | N/A (Risk was never moved) | None (Clean sale) | High (If the hedge fund defaults) |
Future Outlook
Next 12–24 Months
The era of US Mega-Bank Adoption. Historically, European banks executed 80% of global CRTs. Through 2027, as the final US implementation of Basel III Endgame solidifies, American Tier-1 and super-regional banks will enter the market aggressively. JPMorgan, Citi, and US Bancorp will utilize CRTs not just for specialized corporate lines, but for massive tranches of vanilla auto loans and consumer credit cards, driving total global CRT issuance past $30 billion annually.
Next 3–5 Years
The scaling of Retail Democratization via BDCs. By 2030, the double-digit yields of CRTs will no longer be restricted to institutional sovereign wealth funds. Mega-asset managers like Blackstone and Ares will increasingly package their CRT risk-taking portfolios into publicly traded Business Development Companies (BDCs) or interval funds. This will allow high-net-worth retail investors to indirectly provide capital relief to Wall Street banks, further integrating retail liquidity into institutional shadow banking.
Next 10 Years
The Systemic Stress Test and Algorithmic Auditing. By the mid-2030s, the opacity of “blind pool” CRTs will face a reckoning. Following a localized credit crisis where private funds struggle to pay out on synthetic guarantees, regulators will mandate algorithmic transparency. Banks will be forced to use zero-knowledge proofs and blockchain-based smart contracts to cryptographically prove the health of the underlying CRT loan pools to regulators in real-time, without exposing the specific identities of the corporate borrowers to the shadow lenders.
Most Likely Scenario
Capital Relief Trades are the inevitable thermodynamic reaction to over-regulation. You cannot force a bank to hold massive amounts of dead capital without the market inventing a synthetic bypass. By shifting the default risk from highly regulated, fragile banks to unregulated, highly capitalized private credit funds, CRTs arguably make the banking system safer. However, they ensure that the next global credit crisis will not unfold on the transparent balance sheets of Wall Street, but within the opaque, unmapped ledgers of the shadow banking system.
Key Takeaways
- Basel III regulations force banks to hoard massive amounts of cash against their loans (Risk-Weighted Assets), destroying their profitability and lending capacity.
- Capital Relief Trades (CRTs) bypass this by allowing banks to synthetically transfer the risk of loan default to private credit funds using exotic insurance contracts.
- The bank never actually sells the loan. The corporate borrower is completely unaware that a hedge fund is secretly on the hook if they go bankrupt.
- Private credit funds buy this risk because it grants them access to pristine, diversified bank loan portfolios that yield 10% to 15%+.
- While CRTs make banks safer, they shift massive amounts of systemic credit risk into the opaque “shadow banking” sector, creating dangerous blind spots for regulators.
Glossary
Basel III Endgame: An international regulatory framework requiring banks to maintain higher capital leverage ratios and stricter risk-weighted asset calculations to prevent systemic collapse.
Blind Pool: A portfolio of loans where the investors providing the insurance are not allowed to know the exact names of the corporate borrowers, preventing insider trading.
Credit Default Swap (CDS): A financial derivative or contract that allows an investor to “swap” or offset their credit risk with that of another investor. The core mechanism behind a synthetic CRT.
Mezzanine Tranche: The middle layer of risk in a securitization. In a CRT, the private credit fund usually buys the mezzanine tranche (absorbing losses from 0% to 10%), protecting the “Senior” tranche held by the bank.
Risk-Weighted Assets (RWA): A bank’s assets or off-balance-sheet exposures, weighted according to risk. High RWA requires the bank to hold more capital in reserve.
Synthetic Securitization: Transferring the risk of a portfolio of assets to investors through the use of credit derivatives or guarantees, rather than physically selling the assets.
Sources
International Monetary Fund (IMF): The Rise of Synthetic Risk Transfers and Shadow Banking Convergence
European Banking Authority (EBA): Report on the STS Framework for Synthetic Securitization
Ares Management Corporation: The Investment Case for Alternative Credit and Capital Relief Trades
Federal Reserve Board: Basel III Endgame Capital Requirements and RWA Optimization
S&P Global Ratings: Evaluating Counterparty Risk in Blind Pool Synthetic Risk Transfers